Since the SpaceX IPO, shares have struggled. The headlines have turned ugly. And the critics who’ve been wrong about Elon for 20 years are suddenly feeling very bold.
But according to legendary investor Tim Bohen, the man who called Tesla before shares exploded 1,216%...
Elon is preparing to shock the world again.
He confirmed it himself…
“I see a path to SpaceX being worth orders of magnitude more than the current Earth economy.”
— Elon Musk
It’s why Tim has just released a free briefing with all the details of Musk’s bold new plan – and how to get positioned today without buying shares of SpaceX or Tesla.
Verizon Q3 Earnings Beat: Is the Turnaround Finally Taking Hold?
Posted On Oct 26, 2026 by Ian Cooper
Verizon (NYSE: VZ) gave investors a reason to feel better about its business. The telecommunications company beat Wall Street’s third-quarter earnings expectations, raised its full-year outlook, and delivered a sharp improvement in customer growth.
Table of Contents
For investors, the appeal goes beyond one beat. Verizon needs to show it can attract customers while keeping the business profitable. Selling more service through expensive promotions can help subscriber numbers, but it does not necessarily leave shareholders better off. This quarter offered encouraging evidence that the company is making progress on both fronts. Still, a revenue miss shows there is room for improvement.
That makes this a mixed report at the top line, even with the stronger profit performance. Investors should distinguish between a company earning more than expected and bringing in more sales than expected. Verizon accomplished the former. Compared with a year earlier, adjusted earnings increased 8.3%, while total revenue rose 1.5%. Equipment revenue fell 9% as customers kept phones longer and the company reduced device subsidies.
Customer Growth Provides a Bigger Surprise
The most encouraging number was Verizon’s addition of 406,000 net postpaid phone subscribers. These are customers who pay for service through a monthly bill.
Analysts expected about195,000 additions. However, Verizon brought in more than twice the number anticipated. That matters because wireless providers compete for customers who can choose among several carriers. Winning an account creates the opportunity to collect recurring payments, sell additional services, and build a longer customer relationship.
But attracting customers is only half the challenge. Keeping them without constantly offering expensive incentives is just as important. Verizon reported lower customer turnover, while its promotional costs for acquiring and retaining customers declined. Mobility and broadband service revenue increased 2.9% to $23.5 billion.
Taken together, those figures suggest the company’s improvement involves more than simply spending heavily to boost subscriber totals. The next test is consistency. A strong quarter gets investors’ attention. Repeating that performance makes a more convincing case that the business has improved.
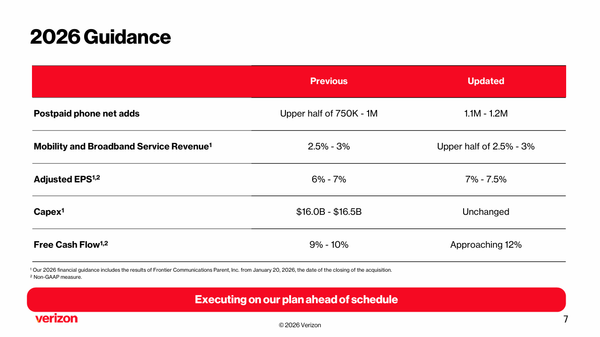
Verizon now expects full-year adjusted earnings of $5.04 to $5.06 per share, representing growth of 7% to 7.5%. Its previous forecast called for growth of 6% to 7%. Management also raised its forecast for postpaid phone net additions to between 1.1 million and 1.2 million. Free cash flow growth is expected to approach 12%, compared with the previous outlook of 9% to 10%.
An AI Opportunity Adds Interest
Verizon also announced an agreement with Amazon Web Services valued at more than $2 billion, adding another potential growth opportunity alongside its wireless business. Reuters described the agreement as an AI infrastructure deal.
The investor logic is straightforward: AI services need communications infrastructure to move information between computing systems and users. That creates opportunities beyond the companies designing chips or developing software.
Still, an announced agreement should not be treated as immediate quarterly revenue. Investors will need to watch its contribution over time. For now, Verizon’s clearest progress is in its core business. Strong subscriber additions, its earnings beat, and higher guidance provide a firmer foundation for optimism.
The next report will help show whether the company can sustain that momentum through the competitive holiday season. If customer growth continues without sacrificing profitability, investors will have a stronger reason to look beyond the initial stock-price bounce.
Can Verizon Turn Subscriber Growth Into Lasting Profits?
Verizon is giving investors more reasons to be optimistic, but the revenue miss leaves something to prove. The key now is turning new customer relationships into lasting, profitable growth while delivering on its higher earnings and cash flow forecasts. The AWS agreement adds potential, but execution in the everyday wireless business will remain essential. If Verizon can keep customers happy, control promotional spending, and strengthen sales, this quarter could mark meaningful progress toward a more durable recovery.
Today’s editorial pick for you
Robinhood Stock: What to Watch in Q3 Earnings
Posted On Oct 26, 2026 by Ian Cooper
Robinhood Markets (NASDAQ: HOOD) will report third-quarter earnings after the market closes on Tuesday, October 27, followed by a conference call at 5 p.m. Eastern. Analysts expect revenue to increase from a year ago, but earnings are expected to fall. That makes profitability a key issue heading into the report.
Table of Contents
Investors will also be watching Robinhood’s growing prediction markets business, where customers can trade contracts tied to the outcome of specific events. It has already become a meaningful source of revenue.
Investors will want to know whether higher spending is temporary or likely to continue. They will also want to hear how that spending could help the company make more money later.
For example, investing in a new product can make sense if it attracts customers and eventually produces healthy profits. But shareholders need evidence that the investment is working. That is why management’s outlook could matter just as much as the quarterly results.
Prediction Markets Are Becoming a Bigger Business
One of the biggest areas to watch is Robinhood’s event contracts business. These contracts let customers trade on whether a particular event will happen.
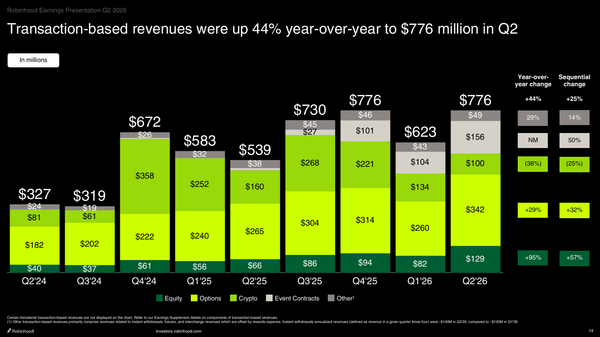
The business generated $156 million in second-quarter revenue, more than Robinhood brought in from either stock trading or cryptocurrency trading during that period. That makes prediction markets much more than a small side business.
In June, Robinhood launched Rothera, an exchange and clearinghouse licensed by the Commodity Futures Trading Commission. It is independently managed through Robinhood’s joint venture with Susquehanna International Group.
This week, investors will get another look at how the business is developing.
They should watch how many contracts customers trade, how much revenue those trades generate, and what management says about demand.
Repeat business will be especially important. A popular event might bring in customers for a short period. The bigger opportunity is getting those customers to return regularly.
Investors will also want to hear about competition and regulation, both of which could affect how quickly prediction markets grow and how profitable they become.
Don’t Overlook the Rest of Robinhood
Prediction markets may get plenty of attention, but Robinhood still needs its other businesses to perform. Last quarter, options trading revenue rose 29% from a year earlier to $342 million. Stock trading revenue jumped 95% to $129 million. Cryptocurrency revenue, however, fell 38% to $100 million. Those results show why having several sources of revenue matters. When one business slows down, another can help make up the difference.
This quarter, investors should look for signs that growth is coming from more than one area.
Customer activity will also matter. Are people adding money to their accounts? Are they trying additional products? Are they using Robinhood more often?
Rosenblatt analyst Chris Brendler recently started covering Robinhood with a buy rating. His positive view focuses on the company’s expansion beyond commission-free trading into a broader financial platform, including more products and opportunities overseas.
The earnings report will give investors a chance to see how that strategy is progressing.
Strong Results Don’t Always Mean a Higher Stock Price
Robinhood’s earnings history offers a reason to watch expectations closely. Continued growth in prediction markets would be encouraging. And so would stronger customer activity across the platform. But the clearest sign of progress would be a convincing explanation of how the company plans to grow profits alongside revenue. Investors already know the company is adding products. This report needs to show how those products can strengthen the business.



No comments:
Post a Comment